 THEREiS
Title :
If AI Scores 100, Why Hire a Tax Accountant? Let's Build It Myself (A Taste of a Double-Entry Bookkeeping Program)
This page was translated from the Korean original using AI. If anything reads oddly, please refer to the original. Read the Korean original →
Introduction
While reading the news this week, I came across a headline that was both funny and sad.
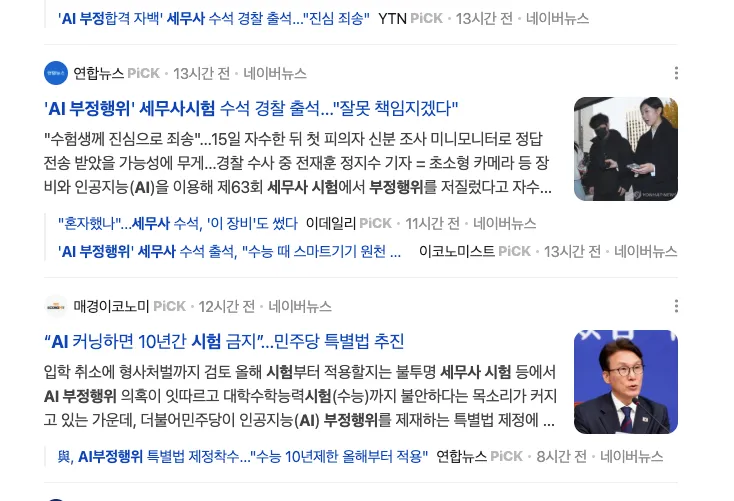
Here’s what happened. The top scorer on this year’s 63rd Korean certified tax accountant exam appeared on YouTube on the 15th, confessed to cheating with AI, and turned themselves in to the police. They reportedly photographed the exam questions with a tiny camera, sent them to a generative AI, and checked the answers on a smartphone. They also admitted to using the same trick on the first round of the CPA exam. Huh? That feels a bit like the Building a Home Secretary project I’ve been working on… but the problem is the person, not the tool.
Anyway, the fallout has been pretty big. The presidential office held an emergency meeting and said it would review how AI devices are monitored ahead of the college entrance exam (Suneung) on the 19th. The ruling party is pushing a special law that bans anyone caught cheating with AI from taking exams for 10 years, and there was even talk of applying it to the Suneung starting this year.
So the world was in an uproar, but over on the other side, people were saying things like this.
“If AI scores 100, who’s going to visit a tax accountant who passed with a 60?”
To pass the first round of the tax accountant exam, you need at least 40 points in each subject and an average of 60 or more across all subjects. So “a 60-point tax accountant” is a jab at the passing line. (Of course, that doesn’t mean real tax accountants are 60-point professionals. This is an exam where the average score on Introduction to Tax Law is 30.)
It was said as a joke, but it hit me pretty seriously. I’m legally required to keep double-entry books. So I hand my books to a tax accountant and pay 80,000 won a month, which adds up to 960,000 won a year.
Honestly, it feels like a waste. My transactions aren’t that complicated. Payments for freelance work come in, I buy equipment, and server fees go out. That’s about it.
So I thought: if AI can score 100 on the tax accountant exam, couldn’t a program I build keep books as simple as mine?
It’s a method where every transaction is recorded in two places, the debit (left) and the credit (right), for the same amount. For example, if you buy a laptop with a card, you record “equipment went up (debit)” and “the card bill you owe went up (credit)” at the same time. So the total debits and total credits across the whole ledger must always be equal. That one rule is all there is to double-entry bookkeeping, and from a programmer’s point of view, it’s a great validation rule.
Part 1 - First, Let’s Check the 2026 Tax Law
Before building the program, I sorted out what current tax law actually requires of me. Everything below is based on the Korean Income Tax Act and its Enforcement Decree as of November 2026.
Who has to keep double-entry books?
The test is the previous year’s revenue. Whether you must keep double-entry books for 2026 is determined by your 2025 revenue.
| Group | Previous year’s revenue | Typical industries |
|---|---|---|
| Group A | 300 million won or more | Agriculture, forestry, fishing, mining, wholesale/retail, real estate sales, etc. |
| Group B | 150 million won or more | Manufacturing, lodging and restaurants, construction, information and communications, etc. |
| Group C | 75 million won or more | Real estate rental, professional/scientific/technical services, education services, etc. |
Businesses below these thresholds, or newly opened that year, only need to keep simplified books. On the other hand, certain professionals such as lawyers, tax accountants, CPAs, and doctors must keep double-entry books regardless of revenue.
What changes once you’re required to keep double-entry books
- More documents to file. When you file your annual income tax return, you have to submit a balance sheet, an income statement, a trial balance, and a tax adjustment statement. If you don’t, it’s treated as if you never filed.
- You have to register a business bank account with the tax office and send and receive business money through it.
- Estimated filing, where you file roughly without books, is effectively off the table. You can’t use the simple expense rate, and only half of the standard expense rate is allowed.
- If you don’t keep books, you get hit with a no-bookkeeping penalty (20% of the calculated tax). The failure-to-file penalty is the greater of 20% of the unpaid tax or 0.07% of revenue. If both apply, only the larger one is charged.
- You also don’t get the bookkeeping tax credit (up to 1 million won) that simplified-book businesses receive when they file with double-entry books.
Once revenue passes a certain size, you become subject to external tax adjustment. The thresholds are roughly double the double-entry thresholds (600 million won for Group A, 300 million for Group B, 150 million for Group C), and the detailed conditions are in Article 131-2 of the Enforcement Decree of the Income Tax Act. In that case, the tax adjustment statement must be prepared by a tax accountant or similar professional. If you ignore this and do the adjustment yourself, it’s treated as not filing. If revenue grows even further and you become subject to faithful filing verification, you also need a separate verification report from a tax accountant.
In other words, this program only makes sense in the range of “required to keep double-entry books, but not subject to external adjustment.”
Changes this year worth noting
- The income deduction limit for the Yellow Umbrella Mutual Aid (a retirement savings program for small business owners) went up by 1 million won in each bracket. For business income of 40 million won or less, it went from 5 million to 6 million won.
- The corporate tax rate went up 1 percentage point in every bracket, but I’m a sole proprietor, so it doesn’t apply to me directly.
Part 2 - Designing the Program
If you break down what the tax accountant’s office does with my books, the flow looks roughly like this.
- Collecting data: tax invoices, card statements, and cash receipts from Hometax (Korea’s online tax service), plus the transaction history of the business bank account
- Journalizing: splitting each transaction into debit and credit accounts
- Ledger and trial balance: grouping by account and making debit and credit totals match
- Closing: year-end work such as depreciation and settling VAT
- Financial statements: balance sheet and income statement
- Tax adjustment: converting accounting profit into taxable income under tax law
- Filing: filing VAT and annual income tax returns on Hometax
Steps 1 to 3 are almost mechanical. The transaction patterns repeat, too. If I set up just a few rules like “AWS charge on the 25th of every month → communication expense,” most transactions get journalized automatically. For transactions that don’t match a rule, my plan is for the AI to suggest an account and for me to confirm it.
The reason I’m not handing the whole ledger to AI is simple. AI can be wrong, but debits and credits must never be out of balance. So the core engine uses rules only, no AI.
The core engine: if debits and credits don’t match, it doesn’t go in the ledger
I built a minimal version in TypeScript.
type AccountType = 'Asset' | 'Liability' | 'Equity' | 'Revenue' | 'Expense';
interface Account {   code: string;   name: string;   type: AccountType; }
interface JournalLine {  account: string;  debit?: number;  credit?: number;}
interface JournalEntry {  date: string;  memo: string;  evidence: 'TaxInvoice' | 'Invoice' | 'CreditCard' | 'CashReceipt' | 'Other';  lines: JournalLine[];}
const ACCOUNTS: Record<string, Account> = {  '103': { code: '103', name: 'Bank Deposits', type: 'Asset' },  '135': { code: '135', name: 'VAT Receivable', type: 'Asset' },  '212': { code: '212', name: 'Equipment', type: 'Asset' },  '253': { code: '253', name: 'Other Payables', type: 'Liability' },  '255': { code: '255', name: 'VAT Payable', type: 'Liability' },  '401': { code: '401', name: 'Sales', type: 'Revenue' },  '814': { code: '814', name: 'Communication', type: 'Expense' },  '831': { code: '831', name: 'Service Fees', type: 'Expense' },};
const ledger: JournalEntry[] = [];
// Post an entry: reject it if total debits and total credits differfunction post(entry: JournalEntry) {  let debit = 0, credit = 0;  for (const line of entry.lines) {    if (!ACCOUNTS[line.account]) {      throw new Error(`Unknown account: ${line.account}`);    }
    for (const v of [line.debit ?? 0, line.credit ?? 0]) {      if (!Number.isInteger(v) || v < 0) {        throw new Error(`Amount must be a non-negative integer (won): ${v}`);      }    }
    debit += line.debit ?? 0;    credit += line.credit ?? 0;  }
  if (debit !== credit) {    throw new Error(`[${entry.date}] ${entry.memo} → Out of balance: debit ${debit} ≠ credit ${credit}`);  }
  ledger.push(entry);}
// Trial balancefunction trialBalance() {  const sums = new Map<string, { debit: number; credit: number }>();
  for (const { lines } of ledger) {    for (const line of lines) {      const s = sums.get(line.account) ?? { debit: 0, credit: 0 };      s.debit += line.debit ?? 0;      s.credit += line.credit ?? 0;      sums.set(line.account, s);    }  }  return [...sums.entries()].map(([code, s]) => {    const acc = ACCOUNTS[code];    // Assets and expenses carry a debit balance; liabilities, equity, and revenue carry a credit balance    const debitSide = acc.type === 'Asset' || acc.type === 'Expense';    return {      code,      name: acc.name,      type: acc.type, ...s,      balance: debitSide ? s.debit - s.credit : s.credit - s.debit    };  });}
I fed it four of my January transactions.
post({ date: '2026-01-05', memo: 'Payment received for freelance development', evidence: 'TaxInvoice', lines: [ { account: '103', debit: 3_300_000 }, { account: '401', credit: 3_000_000 }, { account: '255', credit: 300_000 },]});post({ date: '2026-01-10', memo: 'Laptop for development (card)', evidence: 'CreditCard', lines: [ { account: '212', debit: 2_000_000 }, { account: '135', debit: 200_000 }, { account: '253', credit: 2_200_000 },]});post({ date: '2026-01-25', memo: 'Tax accountant bookkeeping fee', evidence: 'Other', lines: [ { account: '831', debit: 80_000 }, { account: '103', credit: 80_000 },]});post({ date: '2026-01-31', memo: 'Cloud server fee (overseas)', evidence: 'CreditCard', lines: [ { account: '814', debit: 55_000 }, { account: '253', credit: 55_000 },]});Here’s the result.
| code | name           | type      | debit     | credit    | balance   ||------|----------------|-----------|-----------|-----------|-----------|| 103  | Bank Deposits  | Asset     | 3,300,000 |    80,000 | 3,220,000 || 135  | VAT Receivable | Asset     |   200,000 |         0 |   200,000 || 212  | Equipment      | Asset     | 2,000,000 |         0 | 2,000,000 || 253  | Other Payables | Liability |         0 | 2,255,000 | 2,255,000 || 255  | VAT Payable    | Liability |         0 |   300,000 |   300,000 || 401  | Sales          | Revenue   |         0 | 3,000,000 | 3,000,000 || 814  | Communication  | Expense   |    55,000 |         0 |    55,000 || 831  | Service Fees   | Expense   |    80,000 |         0 |    80,000 |
Total debits 5,635,000 / Total credits 5,635,000January profit: revenue 3,000,000 - expenses 135,000 = 2,865,000
Total debits and total credits match exactly. If I deliberately post a typo entry with a 10,000 won debit and a 1,000 won credit, it gets bounced before it ever reaches the ledger.
Rejected: [2026-01-31] Entry with a typo → Out of balance: debit 10000 ≠ credit 1000Korean won is handled only as whole-won integers. If you keep books in floating point, where 0.1 + 0.2 !== 0.3, you’ll end up spending all night at year-end hunting for one missing won.
Part 3 - So Can It Replace a Tax Accountant?
While building the engine, I went back over each thing the tax accountant does for me.
| What the tax accountant does | With a program? | Why |
|---|---|---|
| Bookkeeping (journalizing) | ⭕ | The patterns repeat, so rules plus AI suggestions are enough |
| VAT filing | ⭕ | Hometax data is already digitized |
| Closing and financial statements | 🔺 | Things like depreciation can be turned into rules, but the initial setup is tricky |
| Tax adjustment | 🔺 | It involves judgment calls like “Was this dinner business-related?” |
| External adjustment, faithful filing verification | ❌ | Legally, only tax accountants and similar professionals can do it |
| Tax audits and explanations | ❌ | In the end, a person has to talk to the tax office |
To sum up: the work of “keeping the books” can be replaced, but the work of “making judgments and taking responsibility” is still hard.
This incident shows that rather ironically. AI scored nearly 100 on the exam. But exam questions have correct answers. For real-world questions, the correct answer is decided by the tax office years later. And when you get it wrong, it’s me, not the AI, who pays the penalty.
AI isn’t as all-powerful as you might think, either. According to a paper published late last year by researchers at Douzone Bizon (a Korean business software company), the general-purpose GPT-4 scored 24.1 on Introduction to Tax Law on the tax accountant exam. Their own model, with a tax law knowledge graph attached, scored 86.2. That means you can’t use general-purpose AI as-is; it only becomes useful once you properly attach tax law data. (Newer models will probably do better, but I can’t bet my taxes on “it’ll probably be right.”)
Filing my own taxes myself is perfectly fine. But if I keep someone else’s books with this program and get paid for it, that could violate the Certified Tax Accountant Act. This is strictly for my own business.
So here’s my tentative conclusion for now.
Hmm. I already have plenty of projects I’ve started and haven’t finished, so if I start this one too, when am I ever going to wrap things up? Today was just me thinking through whether tax work could be simplified with AI or a program, so if the chance comes along someday, I think building an AI program that handles tax work wouldn’t be a bad idea. That’s today’s conclusion.
When you take an exam, play fair
Bye.
This post was put together by a sole proprietor, not a tax professional, from laws and sources as of November 2026. Before you actually file, double-check against the Korea Law Information Center or the National Tax Service.
References (in Korean)
- Top scorer on tax accountant exam turns himself in for ‘AI cheating’… police vow “swift and strict investigation” (News Tomato)
- Two proctors per room, yet ‘AI cheating’ caught only by confession (Financial News)
- ‘Alone with 100 on a test averaging 30’… tax accountant exam top scorer and the ‘AI glasses suspicion’ (Weekly Kyunghyang)
- Practicing tax accountant: “A perfect 100 is impossible… I’d even file a criminal complaint” (Wikitree)
- Emergency meeting chaired by policy chief: “Intensive review of proctoring so there’s no AI cheating on the Suneung” (Yonhap News)
- Who must keep double-entry books, and what changes when you do (Glass Wallet)
- 2026 income tax filing for business owners: what’s changed? (Heumtax)
- Douzone NOVA scores 86.2 on Introduction to Tax Law (TaxWatch)
- Korea Law Information Center - Income Tax Act
Loading comments...